Informa plc – Half year results

informa2Informa plc has announced half year results for the six months ended 30 June 2013.
Financial highlights

  • Group organic revenue growth (continuing) of 1.2% to £566.7m (H1 2012: £562.6m)
  • Adjusted operating profit (continuing) up 2.7% to £162.0m (H1 2012: £157.7m)
  • Improvement in H1 adjusted operating margin (continuing) to 28.6% (H1 2012: 28.0%)
  • Adjusted diluted EPS growth (continuing) of 5.0% to 18.9p (H1 2012: 18.0p)
  • Dividend increased – interim dividend raised 6.7% to 6.4p (H1 2012: 6.0p)
  • Corporate Training disclosed as asset held for sale and results classified as discontinued
  • Statutory loss for the period of £56.3m (H1 2012: £41.9m loss), reflecting loss from discontinued operations of £115.7m
  • Strong cash flow – cash conversion rate (continuing) of 70% (H1 2012: 74%)
  • Net debt/EBITDA ratio of 2.4 times (H1 2012: 2.3 times)

 Operational highlights

  • Events division (continuing) organic profit growth of 18.6%
  • 147 large events run in H1, delivering double-digit organic revenue growth
  • 20% of Group revenue (continuing) from emerging markets in the last 12 months (H1 2012: 18%)
  • Deferred income growth of 7% at constant currency
  • Incremental cost reduction programme implemented at PCI
  • Agreed disposal of Corporate Training businesses for up to USD 180m
  • Exit from small conference businesses in Spain and Italy
  • Appointment of Director of Open Access within Academic Information
  • Chief Executive succession plan announced


Peter Rigby, Chief Executive, said:

“It has been a very busy six months for Informa that has resulted in another strong financial performance and further improvement to the underlying quality of earnings. The sale of our non-core Corporate Training businesses will leave us leaner and more resilient, with a sharper focus on higher growth assets offering an attractive return on capital. This is illustrated by the positive organic growth across our continuing operations in H1, the highlight of which was almost 19% organic profit growth in Events.

The outlook for the second half is good and after adjusting for modest dilution from the Corporate Training transaction, underlying expectations for the full year are unchanged. Encouragingly, there are some tentative signs of improvement in areas that have proved particularly tough in recent years, providing grounds for cautious optimism.

Our strong performance has led to another increase in the interim dividend, up 6.7% to 6.4p and our leverage remains comfortably within our target range at the end of June, before receiving the cash proceeds for Corporate Training.

I recently announced my intention to retire as Chief Executive at the end of the year. I have been with the Group for 30 years and feel now is the right time to hand over the reins, with Informa in great shape financially, operationally and culturally. Stephen A. Carter will take over as CEO from 1st January 2014, following a thorough handover process.”

Click here for the full announcement.

UK, London

Related articles:

Progressive Digital Media Group – first 6 months results

progressiveBusiness information group Progressive Digital Media Group has announced its unaudited interim report for the six months ended 30 June 2013. Business Information, which includes Business Intelligence and Events and Marketing, now accounts for almost 98% of Group revenues and earnings. Business Information revenues grew by 11.3% in the first half (over the corresponding period in 2012), while Events and Marketing revenues fell. They were adversely impacted by the rephasing of a number of events from the first half of last year to the second half of this year.

Highlights

Strong first half results, a robust balance sheet and continued investment provide the foundation for further growth.

  • Group revenue increased by 10.3% to £28.6m (2012: £25.9m)
  • EBITDA increased by 33.9% to £4.8m (2012: £3.6m)
  •  Adjusted EBITDA increased by 23.5% to £5.4m (2012: £4.3m)
  • Adjusted EBITDA Margin increased to 18.8% (2012: 16.8%)
  • Reported profit before tax grew by 77.2% to £3.5m (2012: £2.0m)


Mike Danson, Chairman of Progressive Digital Media Group Plc, commented:

“Our first half results reflect good performances across multiple channels. We are increasingly confident that our focus on building premium Consumer and Technology Business Information services will provide the basis for continued long-term profitable growth. With this in mind, we are accelerating our investment in our sales force, product offering, content and delivery platforms in the near to medium-term.”

For the full announcement and notes on the accounts figures, click here

UK, London

Related articles:

ITV acquires Big Talk

itvITV plc today has acquired Big Talk Productions and associated companies (Big Talk), the producer of award winning programmes Friday Night Dinner, Him & Her and Rev as well as films including Shaun of the Dead, Hot Fuzz and The World’s End.

ITV will pay an initial cash consideration and further capped cash payments contingent on Big Talk’s future performance.  The initial cash consideration will be dependent on the 2012/13 financial performance and is expected to be in the region of £12.5m.  The further capped cash payments are payable on the delivery of significant profit growth over the next five years.

UK, London

Related articles

Pearson half-year results: FT Group’s Mergermarket business put up for sale

Pearson2Pearson has published its half year results, at the same time  announcing that it is exploring the possibility of selling financial intelligence business Mergermarket. John Fallon, chief executive, said that while Mergermarket is a growing business, it does not fit with Pearson’s goal to be a market-leading education company.

Highlights

  • Pearson is exploring the possible sale of Mergermarket, the financial intelligence, data and analysis business. Pearson has appointed J.P. Morgan Cazenove to advise on the process.
  • John Fallon, the chief executive of Pearson, stressed that the paper was not for sale.
  • Pearson revenues up 5% to £2,243M
  • FT Group Revenues flat – £217M in 2013, £216M in 2012
  • FT Group Operating Profit up to £26M from £21M in 2012
  • Penguin Random House merger completed on 1 July 2013; strong growth at Penguin (up 14%) in the first half.
  • Adjusted operating profit £50m lower at £137m, including £37m of gross restructuring charges and, in addition, investments to support new product launches in the second half.
  • Adjusted earnings per share down 4.9p to 9.9p including restructuring charges.
  • Interim dividend up 7% to 16p.

Click on the Financial Highlights table below to enlarge the view

Pearson Half-Year Results 2013

John Fallon, chief executive, said: “In trading terms, 2013 has begun much as we expected. In general, good growth in our digital, services and developing-market businesses continues to offset tough conditions for traditional publishing. Our strategy is to transform Pearson into a single operating company that is sharply focussed on the biggest needs in global education and on measurable learning outcomes. With our restructuring programme on track and the reorganisation of the company under way, we are making significant progress towards that goal.”

Read the full announcement here.

UK, London

Related links:

Omnicom Group and Publicis Groupe to merge

publicis OmnicomOmnicom Group and Publicis Groupe are to merge, creating the world’s largest communications, advertising, marketing and digital services company, with combined 2012 revenue of $22.7 billion / €17.7 billion. Based on closing prices on July 26, 2013, Publicis Omnicom Group will have a combined equity market capitalization of approximately $35.1 billion / €26.5 billion. The merged group will have more than 130,000 employees. The merger is expected to generate efficiencies of $500 million / €377 million.

The Publicis Omnicom Group will include BBDO, Saatchi & Saatchi, DDB, Leo Burnett, TBWA, Razorfish, Publicis Worldwide, Fleishman-Hillard, DigitasLBi, Ketchum, StarcomMediaVest, OMD, BBH, Interbrand, MSLGROUP, RAPP, Publicis Healthcare Communications Group (PHCG), Proximity, Rosetta, CDM, ZenithOptimedia and Goodby, Silverstein & Partners.

Maurice Lévy, Chairman and CEO of Publicis Groupe, said: “The communication and marketing landscape has undergone dramatic changes in recent years including the exponential development of new media giants, the explosion of Big Data, blurring of the roles of all players and profound changes in consumer behavior. This evolution has created both great challenges and tremendous opportunities for clients. John and I have conceived this merger to benefit our clients by bringing together the most comprehensive offering of analog and digital services. Equally important, it will offer our talented people new avenues for growth and success at the crossroads of strategic intelligence, creativity, science and technology.”

John Wren, CEO of Omnicom, said: “Both Maurice and I believe this new company reflects our vision of retaining the best talent, attracting an incredible roster of clients and leading innovation. Omnicom and Publicis Groupe are reshaping the industry by setting a new standard for supporting clients with integrated messaging across marketing disciplines and geographies. This combination will enable us to leverage the skills of our exceptionally talented people, our broad product offering, enhanced global footprint, and tremendous roster of global and local clients. In short, we believe this is a merger that will set our new company on a path to accelerated growth, with long-term benefits for clients, employees and shareholders.”

The Publicis Omnicom Group is being announced as a merger of equals. Publicis Groupe and Omnicom’s CEOs will lead the company as co-CEOs through an initial integration and development period of 30 months, following which Mr. Lévy will become non-executive Chairman and Mr. Wren will continue as CEO. The company will have a single-tier board with 16 members, consisting of the two co-CEOs and seven non-executive directors from each company.

For the first year following the closing of the transaction, Bruce Crawford, currently Omnicom Chairman, will be the non-executive Chairman of Publicis Omnicom Group. He will be succeeded by the current Publicis Groupe Chairperson, Elisabeth Badinter, as non-executive Chairperson for the second year following the closing of the transaction.

The transaction is a cross-border merger of equals under a holding company, Publicis Omnicom Group, in The Netherlands. The Group’s operational head offices will continue to be based in Paris and New York. The merger is expected to be tax-free to the shareholders of both companies. The transaction has been structured so that the shareholders of Publicis Groupe and Omnicom, after special dividends, will each hold approximately 50% of the equity of Publicis Omnicom Group. Publicis Groupe shareholders will receive one newly issued ordinary share of Publicis Omnicom Group for each Publicis Groupe share they own, together with a special dividend of €1.00 per share. Omnicom shareholders will receive 0.813 newly issued ordinary shares of Publicis Omnicom Group for each Omnicom share they own, together with a special dividend of $2.00 per share. In addition, Omnicom shareholders will receive up to two regular quarterly dividends of $0.40 per share if declared and the record date occurs prior to closing.

Publicis Omnicom Group is expected to be listed on the NYSE and Euronext Paris, traded under the symbol OMC, and to be included in the S&P 500 and CAC 40. The transaction is subject to approval by the shareholders of both companies as well as numerous regulatory approvals. It is expected to close in the fourth quarter of 2013 or the first quarter of 2014. Publicis Groupe and Omnicom have expressed the desire to have their shares start trading simultaneously on the day of announcement. As a consequence and because of the time difference, Publicis Groupe has asked Euronext Paris to postpone the trading of its shares to 9.30am New York time / 3.30pm Paris time.

Moelis & Company is financial advisor to Omnicom on the transaction. Rothschild is acting as financial advisor to Publicis Groupe. Legal advisors to Omnicom are Latham & Watkins LLP and De Brauw Blackstone Westbroek N.V. Legal advisors to Publicis Groupe are Wachtell, Lipton, Rosen & Katz; Darrois Villey Maillot Brochier; and NautaDulith N.V. Jones Day provided counsel to Moelis & Company.

USA, New York, NY and France, Paris

Related articles

Euromoney Institutional Investor – interim management statement to July 24, 2013

Euromoney Institutional Investor PLC , the international publishing, events and electronic information group, has issued its Interim Management Statement for the period from April 1 to July 24, 2013.

Trading

Since reporting its interim results on May 16, 2013, trading has continued in line with the board’s expectations as set out in the interim results announcement.

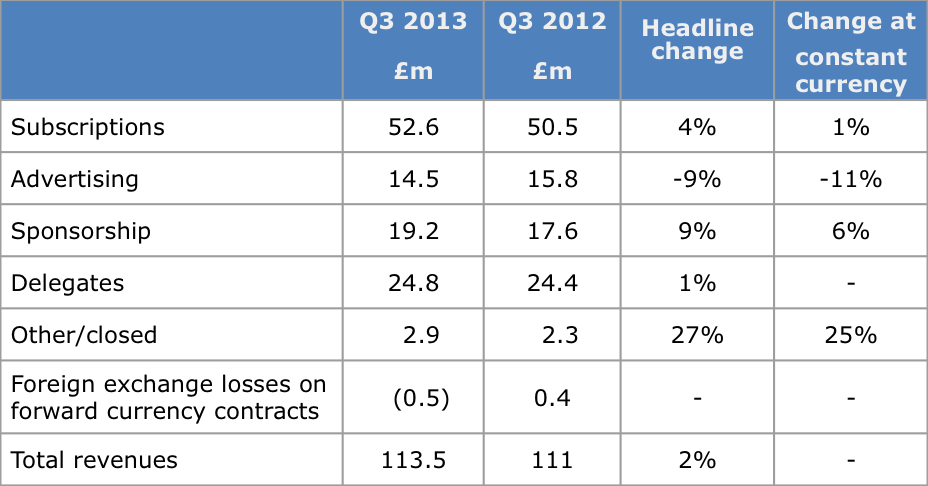
Headline revenues for the quarter to June 30, 2013 increased by 2% to £113.5 million.  The group generates nearly two thirds of its revenues in US dollars and after adjusting for an average sterling-dollar rate for the third quarter of $1.53, against $1.60 a year ago, revenues at constant currency were unchanged.  The increase in revenues from the three small acquisitions completed earlier in the year was largely offset by timing differences on certain subscription accounts.

Subscription revenues increased by 4%, and by 1% at constant currency.  The rate of growth at constant currency was less than the 3% achieved in the second quarter due to delays in the receipt of a few subscription accounts which are recognised on a cash basis.  This timing difference is expected to reverse in the final quarter.  The 11% decline in advertising revenues was consistent with the trend seen over the previous 18 months with advertising from global financial institutions particularly weak.

The third quarter is the most important of the year for the event businesses with many of the group’s largest events held during this period.  Despite the challenging markets, revenues from the group’s bigger events remained robust and the positive first half event revenue trends continued.  Sponsorship revenues increased by 6% at constant currency, partly due to the acquisition in April of CIE, the Australian provider of investment forums for the asset management industry.  Delegate revenues were unchanged.

The following table summarises the year-on-year revenue changes for the third quarter at both headline rates and at constant exchange rates:

Eurononey intrim Jul13


Click on the table for a larger view

Financial Position

Net debt at June 30 was £34.4 million against £38.1 million at March 31. The group’s strong operating cash flows for the quarter were offset by acquisition payments of £12.7 million, including the £9.9 million purchase of CIE, an interim dividend of £8.8 million, and other non-operating cash outflows of £6.4 million.  Movements in the US dollar exchange rate had no significant effect on net debt levels.

Outlook

The broad trading background has not changed significantly since the interim results.  The outlook for US markets, and in particular the profitability of US financial institutions, has continued to improve.  However, European institutions remain focussed on tight cost control and compliance with a tougher regulatory environment while uncertainties persist over some emerging markets, particularly China, and the commodities sector.

July and August are the quietest trading months of the year and while the fourth quarter is the least significant for the group’s event businesses, recent advertising sales trends have been encouraging.  However, as usual at this time of the year, revenue visibility for September, which traditionally accounts for at least 20% of the group’s full year profit, is limited.

The group will continue to invest in technology, marketing and new products to achieve organic growth and focus on revenue synergies from its recent acquisitions.  Overall, trading remains in line with the board’s expectations.

UK, London

Related articles

Informa disposes of its five corporate training businesses

informa2Informa plc is selling its five Corporate Training businesses to Providence Equity Partners for a total consideration of up to $180m. The deal is expected to complete in the third quarter of 2013.

The initial consideration of $165m, consists of $100m in cash (net of indebtedness and working capital adjustments on completion) and a $65m vendor loan. The vendor loan is for a maximum term of 6.5 years and attracts a PIK interest rate of 1% in the first two years, rising to 10% in the third year with a further 1% per annum increase thereafter.

providenceequityThe cash element of the consideration will initially be used to reduce Group net debt. A further cash payment of up to $15m will be received by Informa in 2014 dependent upon the businesses achieving a certain level of revenue in 2013.

In the year ended 31 December 2012, the contribution attributable to the Corporate Training businesses was revenue of approximately $194m (£122m) and adjusted EBITA of $23.5m (£14.8m). As at 31 December 2012 the business had gross assets of $358.8m (£225.7m).

Peter Rigby, Chief Executive, said, “The disposal of our Corporate Training businesses creates a more focused, higher growth, higher margin Events division with more visible and predictable revenue streams, enhancing the underlying quality of Group earnings.

I would like to take this opportunity to thank all of our colleagues within Corporate Training who have worked so diligently and intelligently to develop the businesses through a highly challenging economic period. I believe Providence, with a significant investment already in the education sector, will be an excellent home for the businesses.”

UK, London

Related articles:

Enserve sells Inenco Group to Vitruvian Parners, Management and ICG

inencoEnServe Group, the energy and utility outsourcing business owned by private equity house Cinven, has sold its Energy division, Inenco Group, to funds managed by Vitruvian Partners, management and Intermediate Capital Group Plc. The terms of the deal were not disclosed.

Inenco Group provides businesses with strategic energy management procurement and risk management services. It has over 9,000 clients including corporate, public sector and SME customers. Its services are provided through three specialised brands Inenco, Inenco Direct and NIFES.

Cinven’s most recent portfolio company report on Enserve Group covers the year to March 2012. The Energy division of Enserve vitruvianproduced revenue for that year of £27M (2011: £27.7M) and EBITDA of £9.8M (2011: 8.2 million).

Cinven acquired the parent company EnServe Group (formerly Spice plc) in a public to private transaction in December 2010 for £360 million. The proceeds of the sale will be used to reduce bank debt at the parent company level and invest in the remaining divisions.

Michael Abbott, Chief Executive of Inenco Group, commented: “We’re really excited to be partnering with Vitruvian, who share our vision to consolidate our leading position in the UK and grow internationally with our fantastic client base. Vitruvian also has significant financial resources to support an acquisition programme to accelerate growth.” Abbott went on to say, “Inenco Group’s head office will continue to be based on the Fylde Coast in Lancashire, with NIFES offices in Glasgow, Altrincham and London operating alongside Inenco Direct’s growing presence in Liverpool. Over the course of the next three years, we intend to create new employment opportunities to support the growth in demand for our services, which is fuelled by volatile and rising energy prices and a mass of energy efficiency/carbon legislation.”

UK, London and Lancashire, St Annes

Related articles:

IHS Completes Acquisition of R.L. Polk & Co.

ihs_logo_mpIHS has completed its acquisition of R.L. Polk & Co.  R.L. Polk & Co. consists of two divisions – Polk and CARFAX – that provide market intelligence, tools and analytics and vehicle history information. . Previously, IHS had announced its intent to acquire R.L. Polk & Co. on June 9, 2013; closing occurred on July 15.

polk

The total deal price is $1.4 billion. 90% cash and 10% equity. The stock issuance has a 2-year lock up. 50% of shares can be sold after year one and 100% of shares can be sold after year two

R.L. Polk is headquartered in Detroit and has $400 million of current annual revenue, 75% recurring revenue with 90%-plus renewal rates. 60% of its revenues come from the CARFAX brand and 40% from the Polk Division.

The company is principally focused in North America, with 9% of sales in EMEA and 3% in APAC. It has an adjusted EBITDA margin in mid-20 percent range.

“Now that R.L. Polk & Co. is part of IHS Automotive, their comprehensive information on vehicle registrations, ownership and repair allow us to offer auto makers, automotive parts and technology suppliers and dealers an unparalleled suite of products and services that span from portfolio planning to the end of a vehicle’s life,” said Scott Key, IHS president and CEO. “No one has connected automotive information so comprehensively in markets around the world, or created the analytics solutions and tools that we are currently developing to support the strategic decisions of our customers.

“With this acquisition, IHS truly becomes the scaled, global player in the capital-intensive automotive information industry, which also relies heavily on electronics, chemicals, plastics and energy,” Key continued. “The addition of Polk and CARFAX furthers our vision to become the source of information, insight, expertise and knowledge across all of our target industry sectors and to provide converged solutions that create exceptional value for customers.”

Key added that IHS intends to expand Polk and CARFAX globally, building on IHS infrastructure and presence in EMEA, APAC and high-growth markets in Brazil, India, Russia and the Middle East and the combined information and expertise of these great assets.

“The combination of IHS and R.L. Polk & Co. clearly strengthens both companies and creates more growth and greater opportunities to increase value for our customers,” said Stephen Polk, chief executive officer of R.L. Polk & Co. “We look forward to enhancing key information and insight on which our customers have come to rely to make critical decisions.”

USA, Englewood, CO & Detroit, MI

Previous reporting

Related articles:

ITE Group plc – Interim Management Statement for the period April to July 2013

ITEITE Group plc today published its Interim Management Statement for the period from 1 April 2013 to 15 July 2013, incorporating the Group’s third quarter trading period from 1 April 2013 to 30 June 2013.

The statement follows:

Trading Performance

Good trading conditions continue in our core markets and the Group is trading in-line with management expectations. Revenues in the three month period to 30 June 2013 were £95m (2012: £76m). This year’s result includes a contribution from the biennial Moscow International Oil & Gas exhibition along with a first time contribution from Metaltech in Kuala Lumpur, Mayalsia, which the Group acquired in January 2013. On a like-for-like basis revenues for the third quarter were 8% higher than the previous year.

The principal trading highlights in the third quarter were:

·    Mosbuild, the Group’s principal Moscow construction event continued to prove its resilience in the face of continuing competition and grew volumes by 4% to 68,500 sqm.

·    Moscow International Oil & Gas exhibition, performed strongly with volumes up (since the 2011 event) by over 5% to 24,000 sqm (2011: 22,800 sqm).

·    Turkeybuild is the leading construction event in Turkey. The event, which is space constrained, delivered a small increase in volumes selling 36,200sqm (2012: 36,100sqm). Plans are now in place to add capacity at the venue which will provide an opportunity for the event to grow strongly from 2015 onwards.

Business development

The Group continues to execute its strategy of expanding its operations to new markets with potential for further growth. On 11 April 2013, ITE acquired 50% of ECMI based in Kuala Lumpur, Malaysia for an initial consideration of MYR 8.1m (£1.7m) and a deferred consideration of approximately MYR 4.1m (£0.9m) due in April 2014. In addition the Group holds put and call options to acquire the additional equity in 2017 and 2019. ECMI runs a number of small annual exhibitions in the Beauty and Lab technology sector in Malaysia, Vietnam and Indonesia.

Financial position

The Group had net cash of £17m as at 12 July 2013 (2012: net debt of £1.7m), after spending circa £26m on acquisitions and deferred consideration during this financial year.

Outlook

Year to date, the Group has delivered good organic growth supplemented by the continued investment in new businesses which extend the Group’s reach into new emerging markets. As at 12 July 2013, the Group had £184m of sales booked for the current financial year (this time last year: £164m), representing approximately 98% of the consensus revenue expectations for this financial year.

The Group continues to experience good trading conditions in its principal markets and the Board remains confident in the full year outcome.

UK, London

Related articles: